
 LinkedIn
 Instagram

How Cindy used her pensions to prioritise her health and build a business

It’s Pension Awareness Week and I’ve been thinking about the one thing I’d like everyone to know about their pensions. It’s that they have far more control over their retirement than they think.
You’d be surprised by just how many times people have told me they’re way off retirement and then they’ve ended up in a far more empowered position than they knew.
I’ve been working with Dr Cindy Croucher‑Wright over the past few years, and she’s a great example of what can be possible when you take control of your pension pots.
We’re sharing her story this week to show, step by step, how she and anyone can reshape their future with clarity, confidence and a bit of courage.
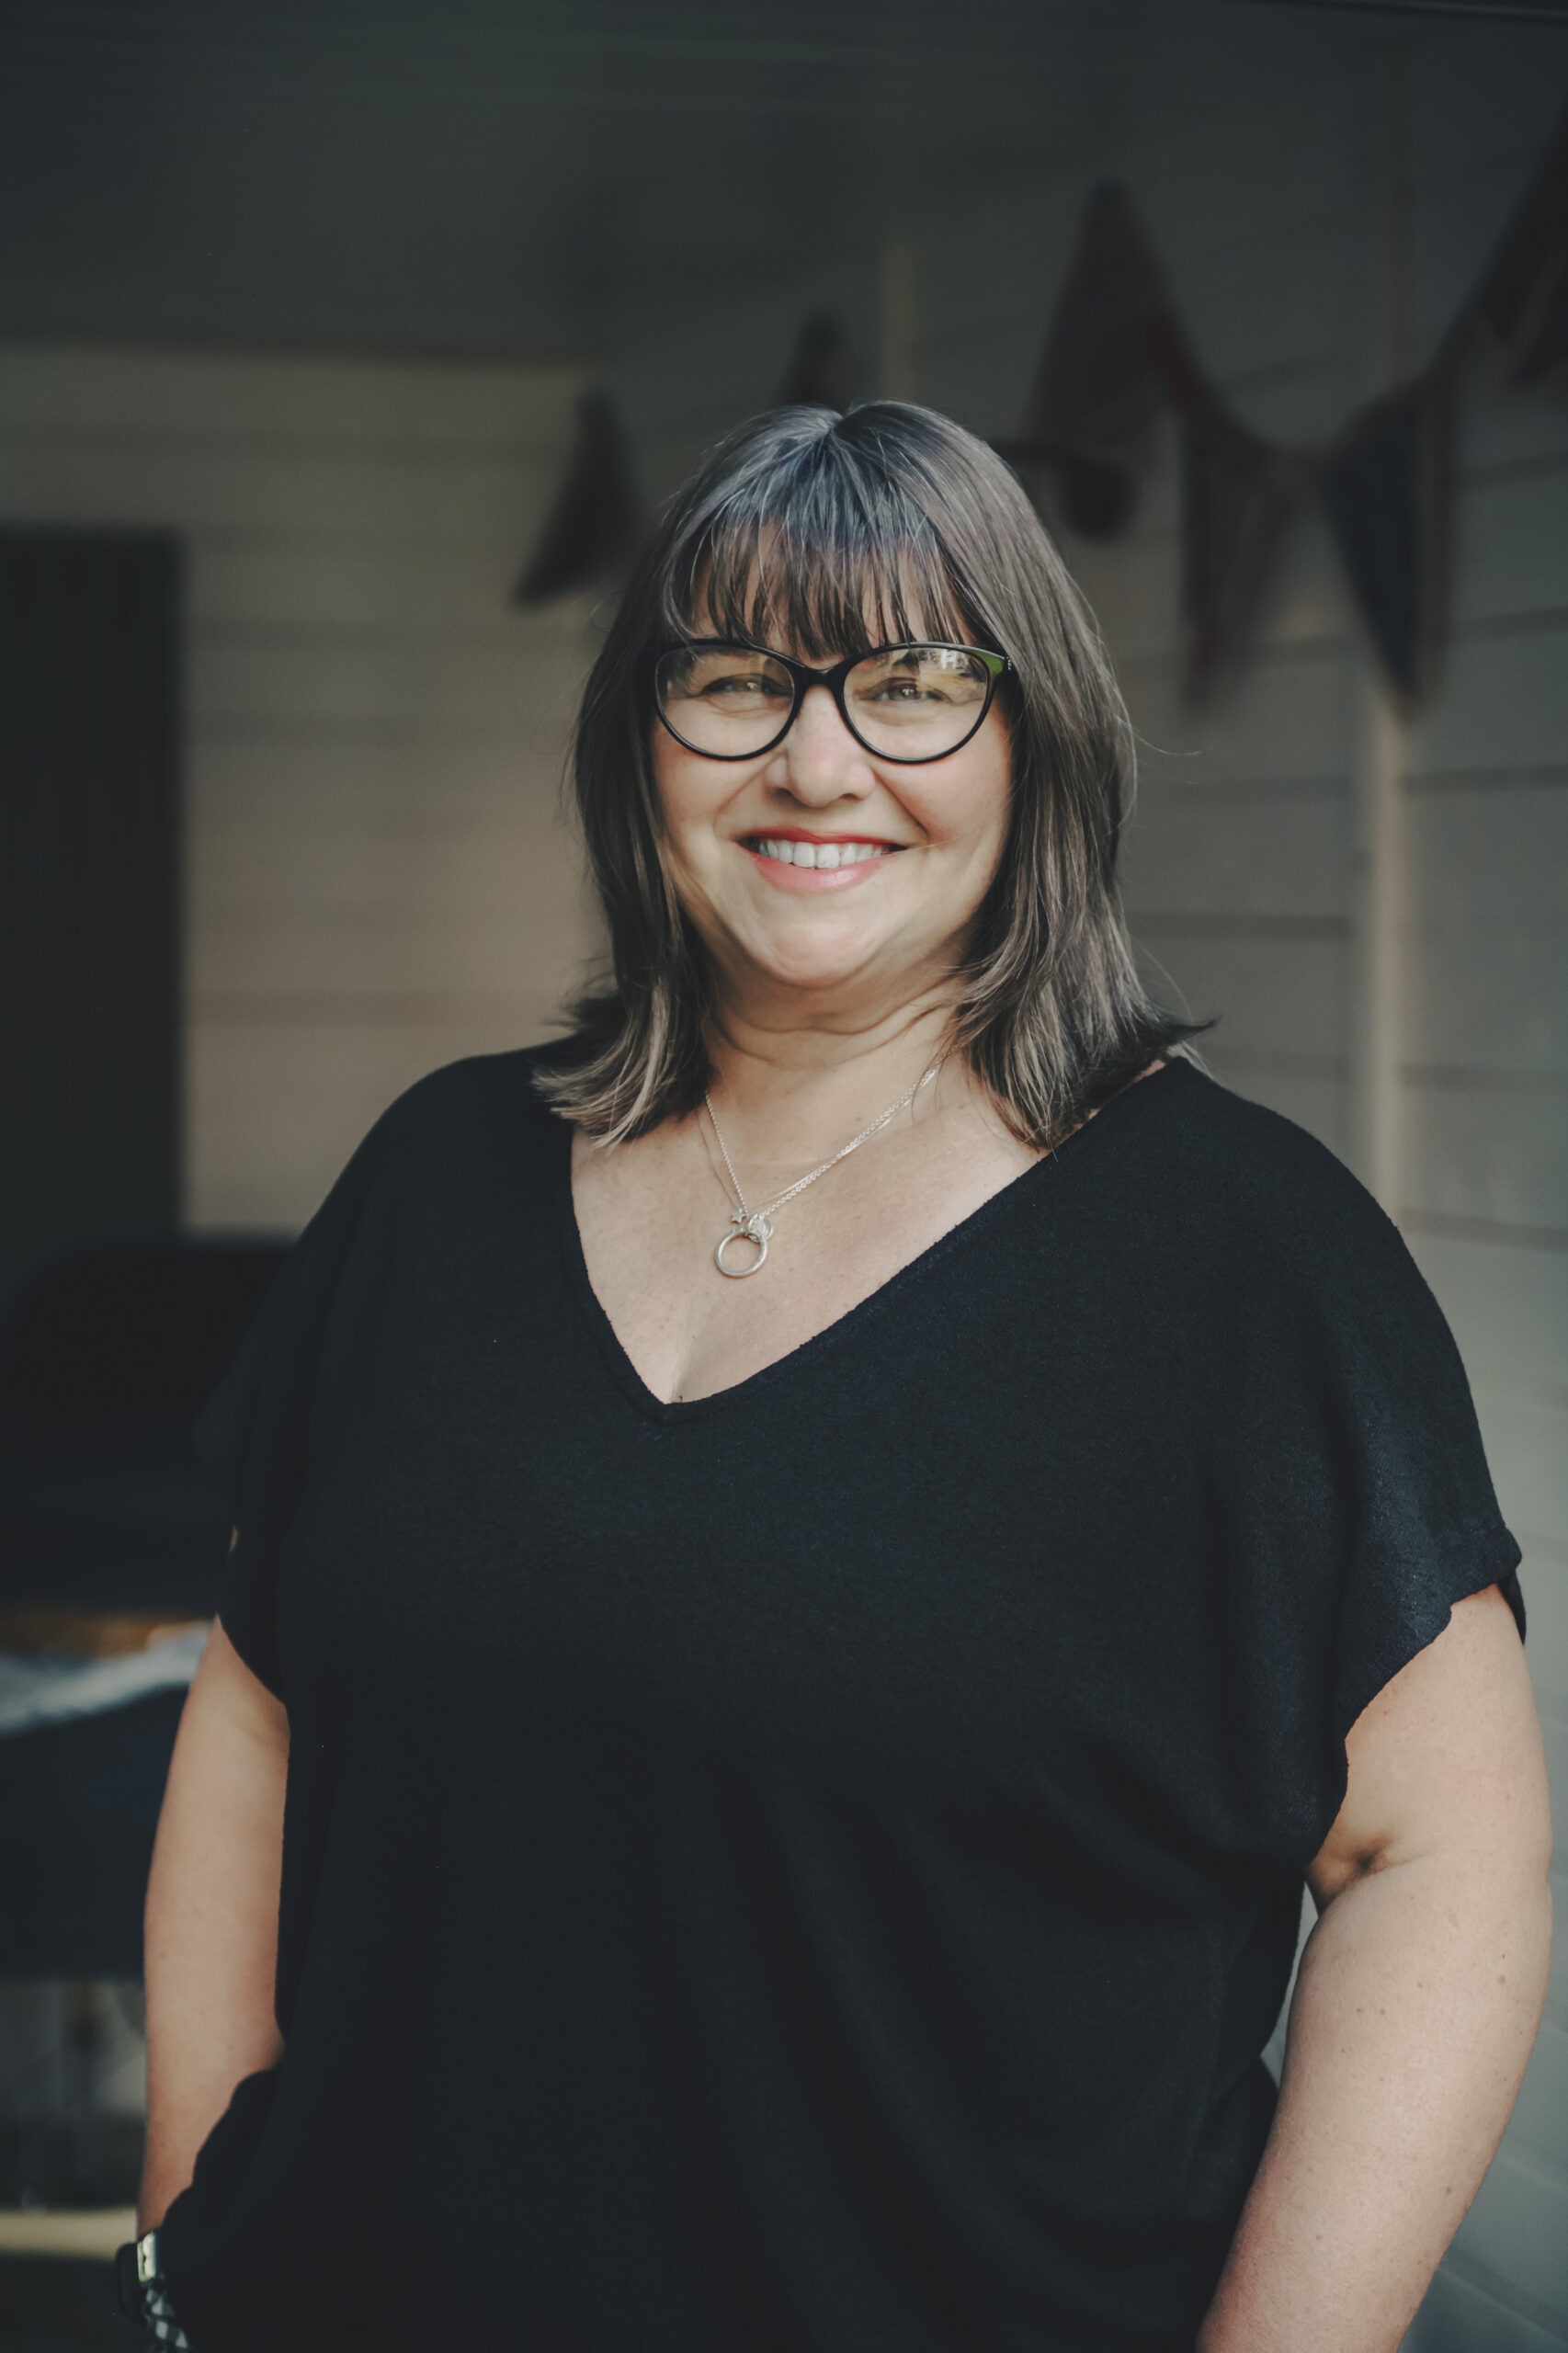
Meet Cindy
After working almost continuously since she was 16, including nearly two decades in higher education, Cindy reached a point where she knew something had to give. At 55, she wanted to retire from her career and build a new chapter as a Reflexologist and Health Coach. She told me:
“It was a midlife health and wellbeing transformation born out of necessity. The menopause left me exhausted, stressed and burnt out. I started asking different questions about what made me happy, how I wanted to spend my time, and what I needed my finances, specifically my pensions, to support that.”
This is exactly the kind of challenge I like to be faced with… how to help someone redesign their life with good planning. Here’s how we approached it.
Step 1: Fact‑finding
Before any advice, I spend time understanding the person behind the numbers.
With Cindy, we explored her goals, lifestyle, health, spending patterns and the pensions she’d built up over decades. She had several pots, each with different rules and options. Getting a clear picture of what she had and what each pension could do, became the foundation of her plan.
It’s also the moment clients share any concerns. Cindy was open about hers:
“I had concerns about whether my pensions would be enough to support me long term, especially as I didn’t want to rely on inheritance. With rising care costs and changes to inheritance tax, it simply isn’t something I can depend on.”
Step 2: Cashflow modelling
Once we had clarity, we moved into detailed cashflow modelling. This is where the “what ifs” get tested.
We modelled different retirement ages, spending patterns, market shocks, tax changes and life events. We explored drawdown, deferring, consolidating, taking tax‑free cash, and the impact that the state pension would have when it’s available at 67. We also tested the need for cash reserves.
For Cindy, this stage was a turning point:
“Through detailed cashflow modelling, we mapped out what retirement could realistically look like and, crucially, how much I needed to earn each month from my business to make my plans sustainable.”
Step 3: Research and recommendations
We analysed each of Cindy’s pensions to determine the most suitable way to access them. We compared her existing arrangements with alternatives, assessed tax implications and made sure everything aligned with her goals, risk profile and capacity for loss.
The outcome was a clear, structured roadmap that we could act on.
Step 4: Implementation
This is where the plan becomes real.
Cindy chose to draw only her workplace pension, giving her a secure foundation while leaving her newly consolidated SIPP invested for future flexibility. The SIPP gave her control over how and when she accesses her pension, and the ability to use drawdown rather than locking into an annuity.
Her new business as a Reflexologist and Health Coach now provides the rest of her income:
“It’s work I genuinely enjoy, giving me purpose as well as the flexibility to design my own lifestyle.”
Step 5: Ongoing reviews
Retirement is a living plan, I continue to review Cindy’s cashflow, update her strategy and adjust things as life evolves.
A midlife transformation empowered by pension planning
Cindy’s pension planning has supported a complete redesign of her health, wellbeing, lifestyle and work.
“After leaving my job, a routine blood test revealed I was pre‑diabetic. It was a wake‑up call that pushed me to prioritise sleep, strength training, nutrition and stress management. Within three months, my blood markers returned to normal. Today, I’m healthier, more intentional and more in control than I’ve been in years. My business gives me autonomy and flexibility, time to go to the gym at a sensible hour, cook healthy meals, walk without rushing. I’m proud that I’ve managed to redesign my work around the life I want to live. I believe this is going to be the strongest chapter yet.”
I often speak to clients when they hit midlife, when pensions suddenly feel very real. Career changes, health shifts, caring responsibilities and lifestyle redesigns all collide with one question: Do I have enough?
Pension Awareness Week exists because so many people reach that moment without clarity. I’m proud to work with Cindy, to share her story, and talk about what’s possible when you understand your pensions and use them intentionally.
This week is the perfect moment to pause and think about what you want your pension to do for you.

Written by Nikki Zammit
Nikki Zammit, Director and Founder, specialises in tailored wealth management and planning and helps clients to realise and deliver their current and future needs. Get in contact if you’d like to talk about your planning needs via or 07725 986666.
Please note, the Financial Conduct Authority does not regulate cashflow planning or tax planning.
A pension is a long-term investment not normally accessible until 55 (57 from April 2028). The fund value may fluctuate and can go down, which would have an impact on the level of pension benefits available. Past performance is not a reliable indicator of future performance.
The tax implications of pension withdrawals will be based on your individual circumstances. Thresholds, percentage rates, and tax legislation may change in subsequent Finance Acts.


Leave a Reply
You must be logged in to post a comment.